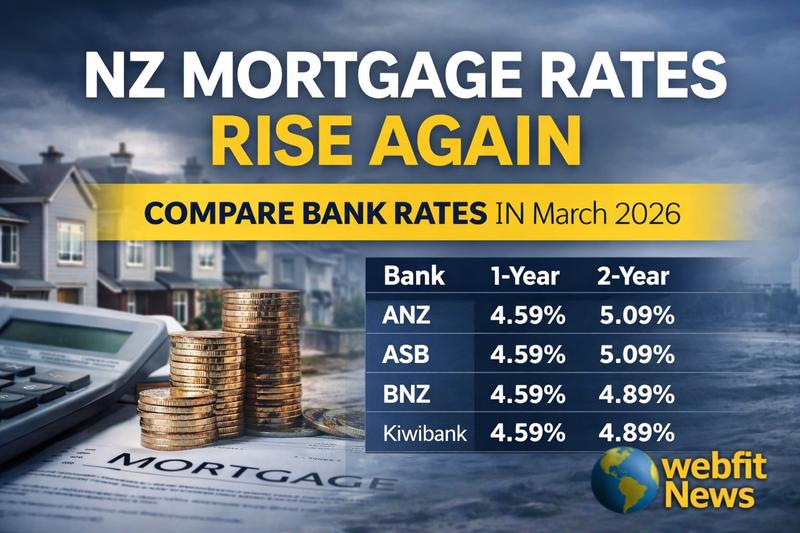
New Zealand’s housing and lending market has taken a sharp and unexpected turn as of 26 March 2026.
Even though the Official Cash Rate (OCR) remains at 2.25%, major banks have started raising mortgage rates again. This is confusing many borrowers and buyers.
So what is really happening?
Let us break it down in simple terms, with real numbers, bank data, and what you should actually do next.
Smart Mortgage Strategy (What You Should Actually Do)
Now the important part. Not theory. Action.
✅ If You Are Refixed Soon:
Do NOT blindly take a 2 or 3-year fixed
Consider 6-month or 1-year flexibility
✅ If You Are a First Home Buyer:
Compare TSB and Co-op first
Use cashback offers (some banks give $5,000+)
✅ If You Are an Investor:
Be careful. Rental yields are under pressure
Term deposits now give up to 5% returns
👉 Property is no longer the easy win.
✅ If You Want Lower Cost Options:
Look at Green Loans
Bank
Offer
ANZ
1% loan for eco upgrades
ASB
1% Better Homes loan
BNZ
Low-rate sustainability loans
👉 This is one of the cheapest borrowing options right now.
Webfit News Perspective (This Matters)
Let us not sugarcoat this.
New Zealand is entering a new phase of uncertainty.
OCR is stable
But real-world borrowing costs are rising
Global events are now directly impacting Kiwi households
This is bigger than just mortgage rates.
This is about: 👉 Cost of living 👉 Housing affordability 👉 Financial stability of families
And honestly, many people are not prepared for this shift.
Final Take
If you take only one thing from this article, take this:
👉 Do NOT assume rates will stay low 👉 Do NOT trust just one bank 👉 Do NOT delay decisions if your loan is due
Because the easy money phase is over.
🧮 Try This: Estimate Your Mortgage Before You Decide
If you are planning to buy a home or refix your loan, it is important to understand what these interest rate changes actually mean for your monthly repayments.
Instead of guessing, you can use this simple tool to get a quick estimate: