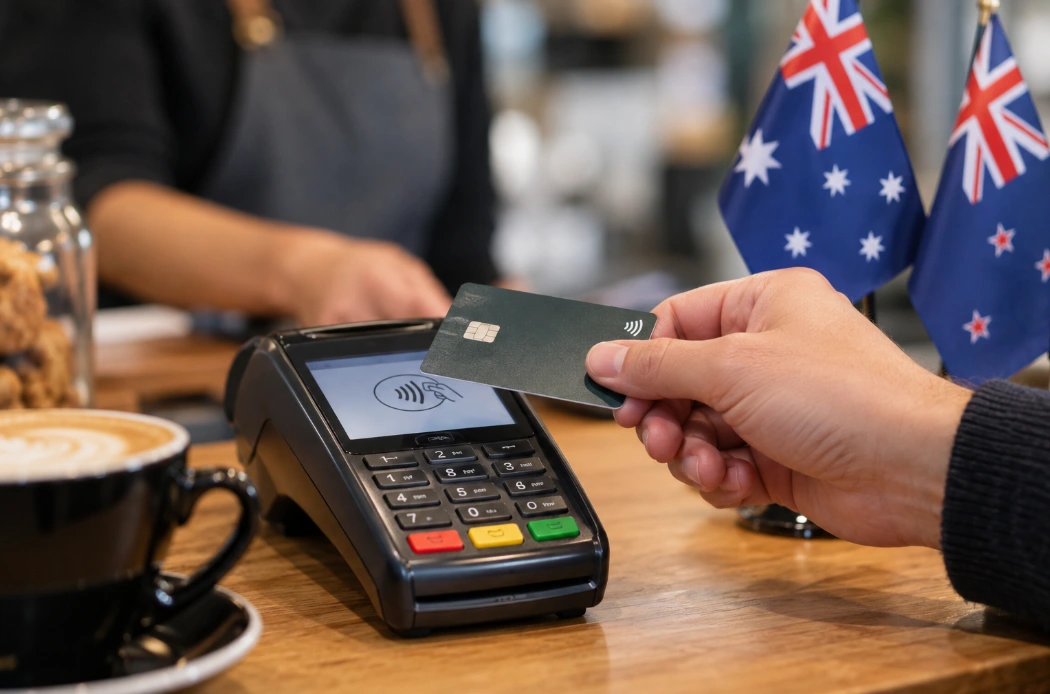
Australians will soon stop seeing an extra fee added when they tap or use many debit and credit cards, with a major overhaul of the country's payment system taking effect from 1 October. Across the Tasman, New Zealand is working towards a similar change, but its proposed ban is still making its way through Parliament.
AUSTRALIA, 21 September 2026: The small percentage added to millions of everyday card transactions is about to disappear in Australia.
From 1 October, surcharges on Visa, Mastercard and Eftpos payments will be eliminated under reforms to Australia's payment system.
For consumers, it should make paying for everything from a morning coffee to dinner at a restaurant simpler. The price displayed should increasingly be the price actually paid rather than another percentage appearing when a card is tapped at the terminal.
But removing the surcharge does not make the underlying cost of processing card payments disappear.
Those costs still have to be paid somewhere, raising a bigger question about whether consumers will eventually pay through higher prices, increased credit-card fees or reduced rewards instead.
Australians expected to save A$1.6 billion
The Reserve Bank of Australia estimates consumers will save about A$1.6 billion a year in surcharges following the changes.
Around 16 percent of Australian businesses currently impose a surcharge, according to figures cited by the Reserve Bank.
The fees have traditionally allowed businesses to recover some of the cost they face when customers use particular payment methods.
Behind every tap is a network of fees involving merchants, banks, card issuers, payment processors and networks such as Visa and Mastercard.
The reforms effectively stop those costs from appearing as a separate surcharge at the checkout.
At the same time, Australia is reducing interchange fees, one of the costs involved in processing card transactions.
For small businesses, the maximum interchange fee covered by the reforms is set to fall from 0.80 percent to 0.30 percent, equivalent to a reduction from 80 cents to 30 cents on a $100 transaction.
The RBA estimates the new interchange limits could save Australian businesses about A$910 million annually.
Credit card rewards could be the trade-off
Consumers who regularly collect credit-card points may notice another side of the reforms.
Major Australian card providers have already begun changing some rewards programmes.
According to The Guardian Australia, changes across the market include limits on the number of points customers can earn, removal of some travel benefits and insurance, higher annual fees and changes to fee waivers.
Some providers have also increased interest rates on unpaid credit.
The reason is relatively straightforward.
Interchange fees have helped finance some of the benefits attached to premium and rewards credit cards. If banks earn less from those transactions, they may look elsewhere to recover some of the lost revenue.
That means an Australian consumer who saves money by no longer paying surcharges could potentially lose value elsewhere if their credit card becomes more expensive or less rewarding.
The effect will not be identical across every card, making it important for customers to read notices from their banks rather than assuming their existing card benefits will remain unchanged.
Could shops simply increase their prices?
There is another possible consequence.
Businesses will still have to pay payment providers even though they can no longer separately pass those costs on as a card surcharge.
Some businesses may therefore incorporate payment costs into their normal prices.
The Reserve Bank has estimated that removing surcharges could result in a one-off increase of around 0.1 percent in shelf or menu prices.
That does not necessarily mean every retailer will increase prices.
Lower interchange fees should reduce part of the cost businesses face, while competition may make it difficult for some retailers to pass every remaining payment expense on to customers.
For consumers, however, there is an important difference.
Instead of seeing one price and discovering an additional charge when paying, payment costs would increasingly become part of the advertised price.
Australian regulators say consumers have indicated they prefer knowing the final price upfront rather than encountering another charge at the payment terminal.
Small businesses remain concerned
The change is more complicated for small businesses.
Large retailers can often negotiate better payment-processing rates because of the enormous number of transactions they handle.
A small café, takeaway shop or independent retailer may have considerably less negotiating power.
Australian small-business representatives have therefore warned that even after interchange fees are reduced, businesses will continue facing payment-processing costs.
Without the ability to surcharge customers directly, those expenses will need to be absorbed by the business or recovered through ordinary prices.
The reforms will also require Eftpos, Mastercard, Visa and large payment acquirers to publish more information about their fees, giving businesses greater visibility over what they are actually paying.
Australia's credit card market could change
The reforms could also change the economics of Australia's highly competitive credit-card rewards market.
Customers who regularly switch cards to collect large sign-up bonuses, a practice sometimes known as credit-card “churning”, may find the strategy less attractive if banks reduce rewards.
Some Australian banks have already increased the period customers must wait before becoming eligible for another sign-up bonus.
For ordinary cardholders, the bigger message may be to look beyond points.
Annual fees, interest rates, travel benefits, insurance, reward conversion rates and other conditions will increasingly determine whether a particular credit card still provides good value after the payment reforms take effect.
What does this mean for New Zealand?
For New Zealanders, Australia's experience is particularly relevant because New Zealand is heading in a similar direction.
The New Zealand Government has proposed banning merchant surcharges on certain in-store EFTPOS, Visa and Mastercard debit and credit card payments.
Under the proposed legislation, the ban would cover card-present transactions, including contactless payments made by physical cards and digital payment methods using the relevant networks.
The proposal does not currently amount to a general ban on every payment fee in every situation. In particular, the legislation has been designed initially around in-store payments, with the ability for the regime to potentially be expanded later.
And importantly, as of September 2026, the legislation has not yet completed its passage through Parliament.
So Kiwi shoppers should not assume Australia's 1 October change automatically applies in New Zealand.
Kiwis already pay millions in surcharges
The scale of the issue in New Zealand is significant.
Government material accompanying the proposed legislation cites Commerce Commission estimates that New Zealand consumers pay as much as NZ$150 million a year in payment surcharges.
Of that amount, an estimated NZ$45 million to NZ$65 million may exceed merchants' reasonable payment-processing costs.
That distinction matters.
Payment processing genuinely costs businesses money. The policy debate is about whether consumers should encounter those costs as an additional charge at the point of payment and whether some surcharges have become higher than the actual cost of providing the payment method.
New Zealand's Commerce Commission says that, under the current system, businesses applying surcharges should generally provide at least one surcharge-free payment option and surcharges should reflect the additional cost of accepting the particular payment method.
The Commission has previously indicated that most in-person surcharge rates should move towards 1 percent or lower.
New Zealand has already reduced some card-processing costs
New Zealand has also been working on the other side of the equation: the fees businesses themselves pay.
New interchange-fee limits for domestically issued Visa and Mastercard cards took effect in December 2025, followed by revised limits for foreign-issued cards in May 2026.
The Commerce Commission estimates its revised pricing standard will save New Zealand businesses hundreds of millions of dollars annually compared with pre-regulation interchange fees.
Further changes affecting commercial and corporate credit cards have also been under consideration.
The reasoning is similar to Australia's approach.
If governments want to remove or restrict surcharges without simply shifting an unreasonable burden onto small retailers, reducing the underlying cost of accepting card payments becomes an important part of the equation.
Australia could provide an early look at New Zealand's future
Australia will now effectively become a useful real-world example for New Zealand.
The first question will be whether removing visible card surcharges genuinely leaves consumers better off.
The second will be what businesses do with the costs they can no longer add separately at the checkout.
And the third will be how banks respond when lower interchange revenue puts pressure on credit-card rewards and other benefits.
For New Zealand consumers frustrated by seeing an extra percentage appear when tapping a card, Australia's reform may look attractive.
For small businesses already operating on tight margins, the picture is more complicated.
Ultimately, eliminating a surcharge does not eliminate the cost of processing a payment. It changes where that cost sits and how visible it is to the customer.
As Australia begins that experiment from 1 October, New Zealand will have a close-up view of what happens when the extra fee disappears from the payment terminal, and whether it simply reappears somewhere else.
Source credit: Based on original reporting by Catie McLeod for The Guardian Australia, published 20 September 2026. New Zealand regulatory context independently researched and added by Webfit News.